
Could a home sale bring in substantial proceeds without making the full amount taxable? That distinction is central to the tax implications of selling a house MI: proceeds are the money from the sale, while your gain is generally measured against your adjusted cost basis. Only some gains may be taxable, depending on your ownership, use of the property, and records.
If you’re preparing to sell, it’s reasonable to wonder whether federal capital gains tax, Michigan income tax, and closing charges apply in the same way. They don’t. Qualifying sellers may exclude up to $250,000 in federal home-sale gains, or up to $500,000 for eligible married couples filing jointly, subject to ownership and use requirements. Michigan’s 4.25% income tax may apply to taxable gains, while real estate transfer tax is a separate closing charge.
This 2026 guide explains how to distinguish sale proceeds, gain, and potentially taxable gain; what the primary-residence rules may mean for your situation; and which improvement records and sale documents to gather. It also covers how to coordinate tax questions with listing and closing milestones. A qualified tax professional can advise you on your individual tax situation.
Key Takeaways
- The tax implications of selling a house MI depend on more than the sale price. Selling expenses and eligible improvements can affect the gain calculation.
- Review how long you owned the home and when you used it as your main residence. Those details may determine whether a federal home-sale exclusion applies.
- Consider the property’s history before estimating taxes, including whether it was a primary home, second home, rental, inherited property, or jointly owned.
- Gather purchase records, improvement receipts, ownership dates, occupancy history, and closing documents for a post-sale tax review.
- Coordinate tax questions, sale timing, and listing milestones early to keep the transaction organized and reduce closing surprises.
Tax Implications of Selling a House in MI: What Could Be Taxable?
The sale price isn’t automatically the amount subject to tax. Start by separating three figures: the amount realized from the sale, your gain or loss, and any gain that may be taxable. This distinction makes the tax implications of selling a house MI easier to assess and helps you identify the records to gather before closing.
Sale price, proceeds, and capital gain are different numbers
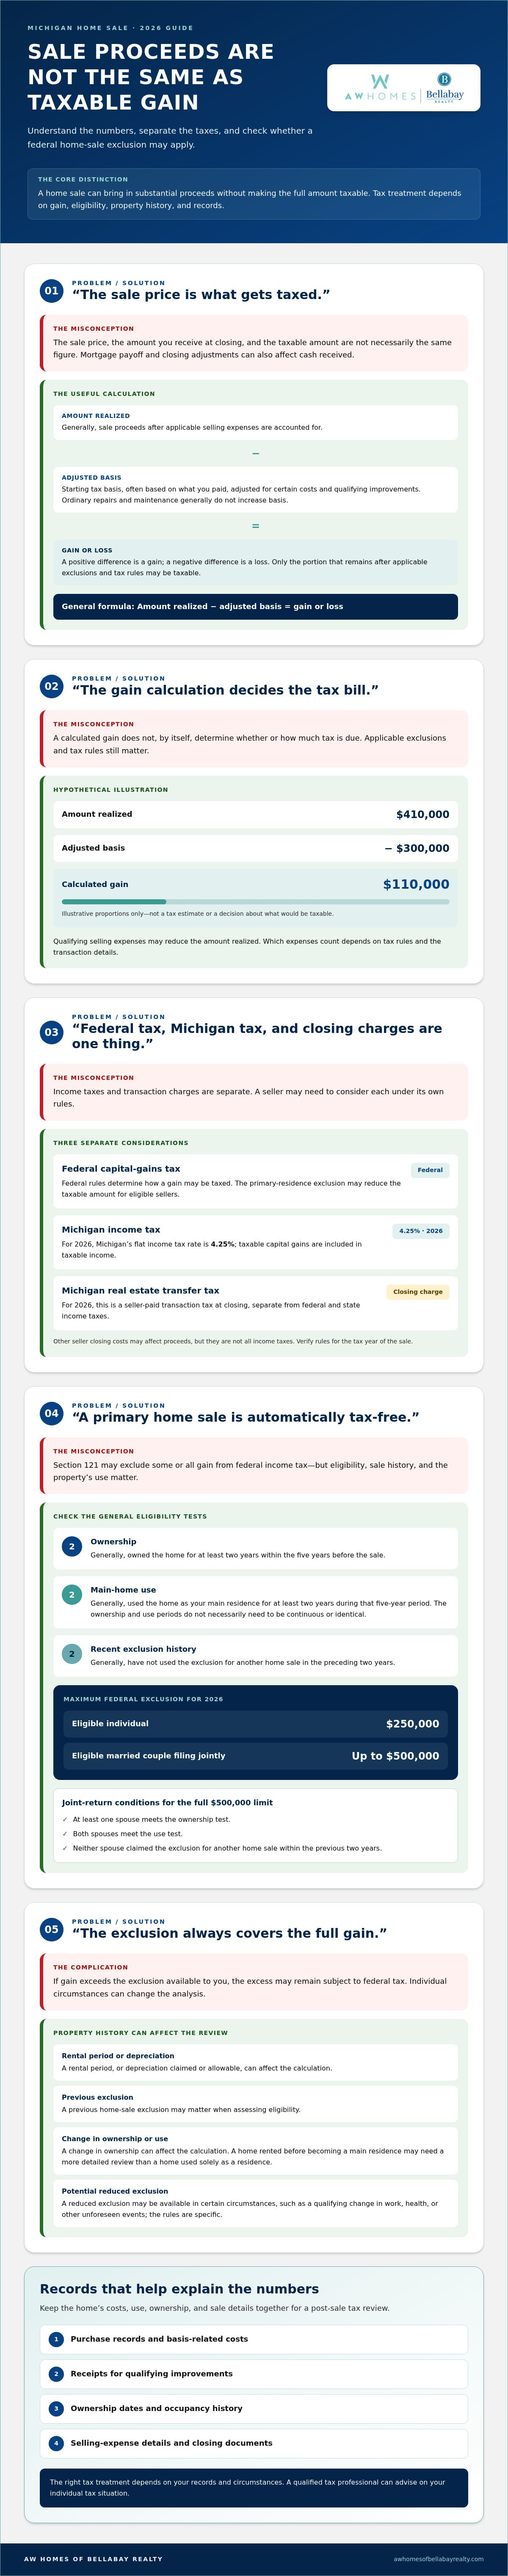
For tax purposes, your home-sale gain is generally the amount realized from the sale minus your adjusted basis in the home. These terms have specific meanings:
- Amount realized: Generally, the sale proceeds after applicable selling expenses are accounted for. The amount you receive at closing may also be affected by items such as mortgage payoff and other closing adjustments.
- Adjusted basis: Your starting tax basis, often based on what you paid, adjusted for certain costs and qualifying improvements. Ordinary repairs and maintenance generally don’t increase basis.
- Capital gain or loss: The difference between the amount realized and adjusted basis. A positive difference is a gain; a negative difference is a loss.
- Taxable gain: The portion of a gain that remains subject to tax after applicable exclusions and tax rules are considered.
General calculation: Amount realized minus adjusted basis equals gain or loss. Qualifying selling expenses may reduce the amount realized, but which expenses count depends on tax rules and the details of the transaction.
Hypothetical example: If a home’s amount realized were $410,000 and its adjusted basis were $300,000, the calculation would show a $110,000 gain. This illustration isn’t a tax estimate. It doesn’t determine whether an exclusion applies or what, if anything, would be taxable in an individual case.
Federal tax and Michigan tax are separate questions
Start with federal treatment. Federal capital-gains rules determine how a gain may be taxed, and the federal primary-residence exclusion may reduce the taxable amount for eligible sellers. Holding period and other circumstances can also matter. For a broad overview of how these rules fit into the U.S. system, see Capital Gains Tax in the U.S.
Michigan income tax is a separate calculation. For 2026, Michigan’s flat income tax rate is 4.25%, and taxable capital gains are included in taxable income. Verify the rules for the tax year of your sale, since state treatment and your circumstances affect the calculation.
Don’t confuse income tax with closing charges. Michigan’s 2026 real estate transfer tax is a seller-paid transaction tax, separate from federal and state income taxes. Other seller closing costs may also affect proceeds, but they aren’t all income taxes. For an overview of transaction stages, see the Michigan home closing process guide. AW Homes helps organize listing and transaction milestones; individualized tax treatment calls for advice based on your records and circumstances.
How the Primary-Residence Exclusion Can Change a Michigan Home Sale
A home sale may qualify for a valuable federal tax rule, but it isn’t automatically tax-free. Section 121 may let eligible sellers exclude some or all of their gain from federal income tax. For 2026, the maximum exclusion is $250,000 for an eligible individual and up to $500,000 for eligible married couples filing jointly. The amount you can claim depends on specific tests and your sale history.
Who may qualify for the federal home-sale exclusion?
The commonly applicable tests look at the five years before the sale. Generally, you must have owned the home for at least two years and used it as your main home for at least two years during that period. Those periods don’t necessarily need to be continuous or identical. The IRS explains the tests and additional rules in IRS Publication 523: Selling Your Home.
In general, a seller may qualify for Section 121 if they meet the ownership and main-home use tests for at least two years within the five years before the sale and haven’t used the exclusion for another home sale in the preceding two years. This is a summary, not a determination of eligibility. Exceptions and individual circumstances can change the analysis.
To claim the full $500,000 limit on a joint return, additional conditions generally apply: at least one spouse must meet the ownership test, both spouses must meet the use test, and neither can have claimed the exclusion for another home sale within the previous two years. A spouse who doesn’t meet every joint-return condition may still have a separate eligibility question. A reduced exclusion may be available in certain circumstances, such as a qualifying change in work, health, or other unforeseen events, but the rules are specific.
When may the exclusion not cover the full gain?
If your gain is greater than the exclusion you’re eligible to claim, the excess may remain subject to federal tax. Other details matter, too. A rental period, depreciation claimed or allowable, a previous home-sale exclusion, or a change in ownership can affect the calculation. For example, a home that was rented before becoming your main residence may need a more detailed review than a property used solely as your home.
Keep records of where you lived, when you owned the property, any rental periods, and previous home sales. Don’t assume that meeting one test settles the rest. Section 121 is federal law, and qualifying for the federal exclusion doesn’t by itself determine Michigan income-tax treatment. Review the state rules for the year you sell.
As you coordinate tax questions with sale timing and transaction milestones, West Michigan home-sale planning can help organize the listing process without promising a tax outcome.
How Home Use, Ownership, and Property History Affect Tax Treatment
The tax implications of selling a house MI can vary with how you used the property, how you acquired it, and who owns it. A sale price is not automatically taxable income, and sellers generally don’t pay income tax on the entire sale price. The potential gain and the rules that apply to your circumstances matter. Transfer taxes and other closing statement items are separate from income tax.
Use this comparison to identify details to organize before estimating a tax outcome. These are starting points, not guaranteed results.
| Property situation | Facts that may affect the analysis |
|---|---|
| Primary residence | How long you owned and used it as your main home, prior exclusion use, and any periods of rental or business use. |
| Second home | Whether it was used as a main home at any point, the ownership and occupancy timeline, and any rental activity. |
| Rental property | Rental income history, expenses, depreciation claimed or allowable, and whether the property also had personal use. |
| Inherited home | How and when ownership transferred, estate or transfer records, the basis used for tax purposes, and any later improvements or use. |
| Jointly owned property | Each owner’s ownership share, acquisition and transfer dates, use of the home, and filing circumstances. |
Primary residence, second home, and rental property
A home used as your main residence may be eligible for the federal home-sale exclusion if the applicable requirements are met. A second home doesn’t qualify solely because you own it; its use and your ownership history matter. For federal rules on main-home sales, including special situations, consult IRS Publication 523.
Rental history adds another layer. Keep records of rental periods and depreciation, including amounts claimed or allowable, for tax review. If you used a home personally for part of the year and rented it for another part, the allocation may require a more specific calculation. Sellers considering an investment-property transaction can explore this Grand Rapids real estate investment guide for investment context.
Inherited, jointly owned, or transferred homes
Inheritance and ownership changes can affect basis, reporting, or how a gain is considered. Don’t assume a particular basis applies based only on the fact that a home was inherited. Gather estate and transfer documents, ownership-change dates, records of each owner’s share, and information about later improvements. Those details help a tax professional review the correct treatment.
Keep income-tax calculations distinct from transfer taxes and other seller charges shown at closing. They affect different parts of the transaction, and a closing statement alone may not answer whether a gain is taxable.
A Michigan Seller’s Tax-Preparation Checklist Before Closing
Good records make it easier to review your home-sale gain and prepare for tax time. Start before closing, while purchase paperwork, improvement receipts, and transaction details are easier to locate. This checklist helps you organize the facts; it isn’t individualized tax advice or a promise about the tax implications of selling a house MI.
Records that can help establish adjusted basis
Gather documents showing what you paid for the property and how its history may affect its tax basis. Capital improvements and routine upkeep can receive different tax treatment, so keep receipts without assuming every project changes your basis. The final treatment depends on the facts and current tax rules.
- Collect purchase records. Save your purchase closing statement and documentation for acquisition costs that may be relevant to your basis.
- Organize improvement receipts. Keep invoices, contracts, and payment records for substantial work, such as documented renovations. Store routine repair and maintenance receipts separately.
- Note property events. Gather records of insurance reimbursements, casualty events, and any periods the home was rented or used for business. These details may affect tax review.
- Track ownership and occupancy. Write down acquisition and transfer dates, each owner’s share, when you used the property as your main home, and any periods of other use.
- Save sale paperwork. After closing, retain the signed sale contract, final settlement statement, and records of selling expenses. Keep any tax forms received from the closing agent with these documents.
- Review the file after closing. Compare the sale documents with your purchase and property-history records. Ask a qualified tax professional to review how current federal and Michigan rules apply to your situation.
Keep taxes and closing costs in separate categories. Michigan’s 2026 real estate transfer tax is $8.60 per $1,000 of sale price, combining state and county taxes, and is separate from federal or Michigan income tax. Other settlement statement items may affect your proceeds, but their treatment depends on the item and applicable tax rules.
For a clearer view of transaction milestones, read the Michigan property closing guide. In Greater Grand Rapids, organized listing and transaction support can help keep sale documents and key dates in view. Plan your West Michigan home sale with the timeline and paperwork in mind.
Plan Your West Michigan Home Sale With Tax Questions in View
A clear plan can make a major transition feel more manageable. For the tax implications of selling a house MI, keep three workstreams distinct: confirm tax questions for your circumstances, organize relevant records, and prepare the listing and transaction timeline. AW Homes helps sellers coordinate the real estate process, while tax calculations, legal interpretations, and filing decisions belong with your tax professional.
Coordinate tax preparation with the real estate timeline
Raise tax questions early, before closing dates and paperwork start to stack up. Share your home’s ownership and occupancy history, rental periods, and improvement records with your tax professional so they can identify what else may be needed. This preparation can happen alongside listing plans, without assuming that a particular sale date will create a tax advantage.
Real estate planning can bring transaction milestones into focus. AW Homes supports sellers with listing guidance, marketing, negotiation, and transaction management. These services help organize the sale from preparation through closing, while your tax professional reviews the tax treatment. Keep the roles clear, the records accessible, and the timeline coordinated.
Prepare for a sale in Greater Grand Rapids
Your next move may be shaped by more than a closing date. In Greater Grand Rapids, including Ada, Caledonia, and East Grand Rapids, local market positioning can be considered alongside your broader plans, whether you’re relocating, downsizing, or moving into a new stage of life. A thoughtful listing plan connects property presentation and sale milestones to those goals without promising a specific price or tax result.
If you’re preparing in Forest Hills, the Forest Hills home-selling guide offers additional context for getting a listing ready. Use it as a real estate planning resource, then bring property-specific tax questions to your tax professional.
With the tax questions identified and documents in order, you can focus on the next decisions: when to prepare, how to position the home, and what transaction milestones to expect. Talk with AW Homes about your home-selling process and next steps when you’re ready to plan your West Michigan sale.
Move Forward With a Clearer Home-Sale Plan
The tax implications of selling a house MI depend on your gain, how you used and owned the property, and which federal or Michigan rules apply. A sale price isn’t automatically taxable income, and organized purchase, improvement, occupancy, and closing records can help clarify what needs review. For your individual tax position, rely on a qualified tax professional. Real estate guidance can help keep listing and transaction milestones organized.
For sellers across Greater Grand Rapids, including Ada, Caledonia, and East Grand Rapids, Angela Worth leads AW Homes of Bellabay Realty. The team’s listing support includes marketing, professional photography, negotiation, and transaction management, helping you approach the sale with a clear plan.
Ready to discuss your home-selling process and next steps? Plan your West Michigan home sale with AW Homes. One well-organized step at a time can make your next transition feel more manageable.
Frequently Asked Questions
Do I pay tax when I sell my house in Michigan?
Possibly, but tax isn’t automatically charged on the full sale price. The key starting point is your gain, generally the amount realized from the sale minus your adjusted basis. Federal rules may exclude some gain for eligible primary-residence sellers. Michigan’s 2026 flat income tax rate is 4.25%, and taxable capital gains are included in taxable income. Your property history and applicable tax-year rules matter, so have your specific situation reviewed.
How much can I exclude when I sell my primary residence?
For 2026, eligible sellers may exclude up to $250,000 of gain from federal income tax, or up to $500,000 for eligible married couples filing jointly. These limits aren’t automatic. Ownership and main-home use requirements, prior exclusion use, filing status, and other circumstances can affect eligibility. The exclusion applies to qualifying gain, not the home’s entire sale price. Review current IRS guidance and your full ownership and occupancy history before relying on it.
How long do I have to live in a house to avoid capital gains tax?
Generally, the federal home-sale exclusion’s use test requires you to have used the property as your main home for at least two years during the five years before the sale. You generally must also have owned it for at least two years in that period. The tests don’t guarantee that all gain will be excluded, and prior sales, rental use, or other details may change the analysis.
Are home improvements tax deductible when I sell my house?
Qualifying capital improvements may increase your adjusted basis, which can reduce the gain used in a tax calculation. Routine repairs and maintenance generally don’t increase basis, and personal home costs aren’t automatically deductible. Keep invoices and payment records, and distinguish substantial improvements from upkeep. The tax treatment depends on the work and your circumstances, so have a qualified tax professional review the records rather than assuming every project reduces taxable gain.
Do I owe Michigan tax if I qualify for the federal home-sale exclusion?
Federal eligibility doesn’t by itself settle your Michigan income-tax treatment. Michigan’s 2026 flat income tax rate is 4.25%, and taxable capital gains are included in taxable income, but the result depends on the gain and rules that apply to your situation. Verify the Michigan treatment for the tax year of your sale and review it separately from the federal exclusion with a qualified tax professional.
Is Michigan transfer tax the same as capital gains tax?
No. Michigan real estate transfer tax is a transaction tax associated with transferring property, while capital gains tax concerns taxable profit from a sale. For 2026, the combined Michigan state and county transfer tax rate is $8.60 per $1,000 of sale price, generally paid by the seller. It’s separate from federal and Michigan income tax, and other settlement statement charges are separate items too.
What records should I keep after selling my Michigan home?
Keep your purchase closing statement, documented acquisition costs, improvement receipts, signed sale contract, final settlement statement, and records of eligible selling expenses. Also save ownership and occupancy dates, rental and depreciation history if applicable, prior home-sale exclusion details, and any tax forms received from the closing agent. These records help a tax professional review your gain and reporting needs, whether your home was in Grand Rapids, Ada, Caledonia, or East Grand Rapids.


