
What if the primary obstacle to your next home isn't the competitive 2026 market, but the absence of a synchronized financial bridge between your current equity and your future evolution? You've likely spent months watching property values in Forest Hills and East Grand Rapids climb, yet the fear of being homeless between transactions or the stress of managing two mortgages simultaneously keeps you anchored. It's a common tension for those seeking more space, better amenities, and a more refined lifestyle. Mastering move-up buyer financial planning Grand Rapids is about more than just numbers; it's about securing your emotional peace of mind during a significant life milestone.
We understand that a high-stakes transition requires professional authority, empathetic reassurance, and a methodical strategy. This guide promises to transform your uncertainty into a clear financial roadmap tailored for the current West Michigan climate, where Forest Hills executive homes often sell in just six days. We'll explore the essential steps to leverage your equity, navigate the 2026 property tax multiplier of 1.027, and execute a concierge-led transition. You don't have to choose between your financial security, your family's comfort, and your next life stage.
Key Takeaways
- Learn to navigate the 2026 Kent County market by viewing your transition as a strategic, unhurried, and intentional life milestone.
- Master move-up buyer financial planning Grand Rapids by calculating net equity, exploring jumbo loan options, and securing a specialized pre-approval.
- Compare the financial advantages of Forest Hills, Ada, and East Grand Rapids to find the perfect balance of school district premiums and lifestyle-driven appreciation.
- Adopt a methodical step-by-step roadmap that prioritizes professional market analysis and strategic timing to eliminate the risk of managing two mortgages.
- Discover the concierge philosophy that ensures your transition is professional, unhurried, and strategic, protecting your emotional security at every turn.
Navigating the 2026 Grand Rapids Real Estate Market Transition
A move-up purchase is more than a simple change in address; it's a strategic life evolution that signals your arrival at a new personal milestone. In the current 2026 climate, transitioning to a larger home in neighborhoods like Forest Hills or Ada requires the perspective of a high-level consultant rather than a standard sales approach. You aren't just looking for more square footage. You're seeking a space that mirrors your growth, supports your ambitions, and provides long-term stability. A successful transition is built upon three essential pillars: financial readiness, precise market timing, and unwavering emotional security.
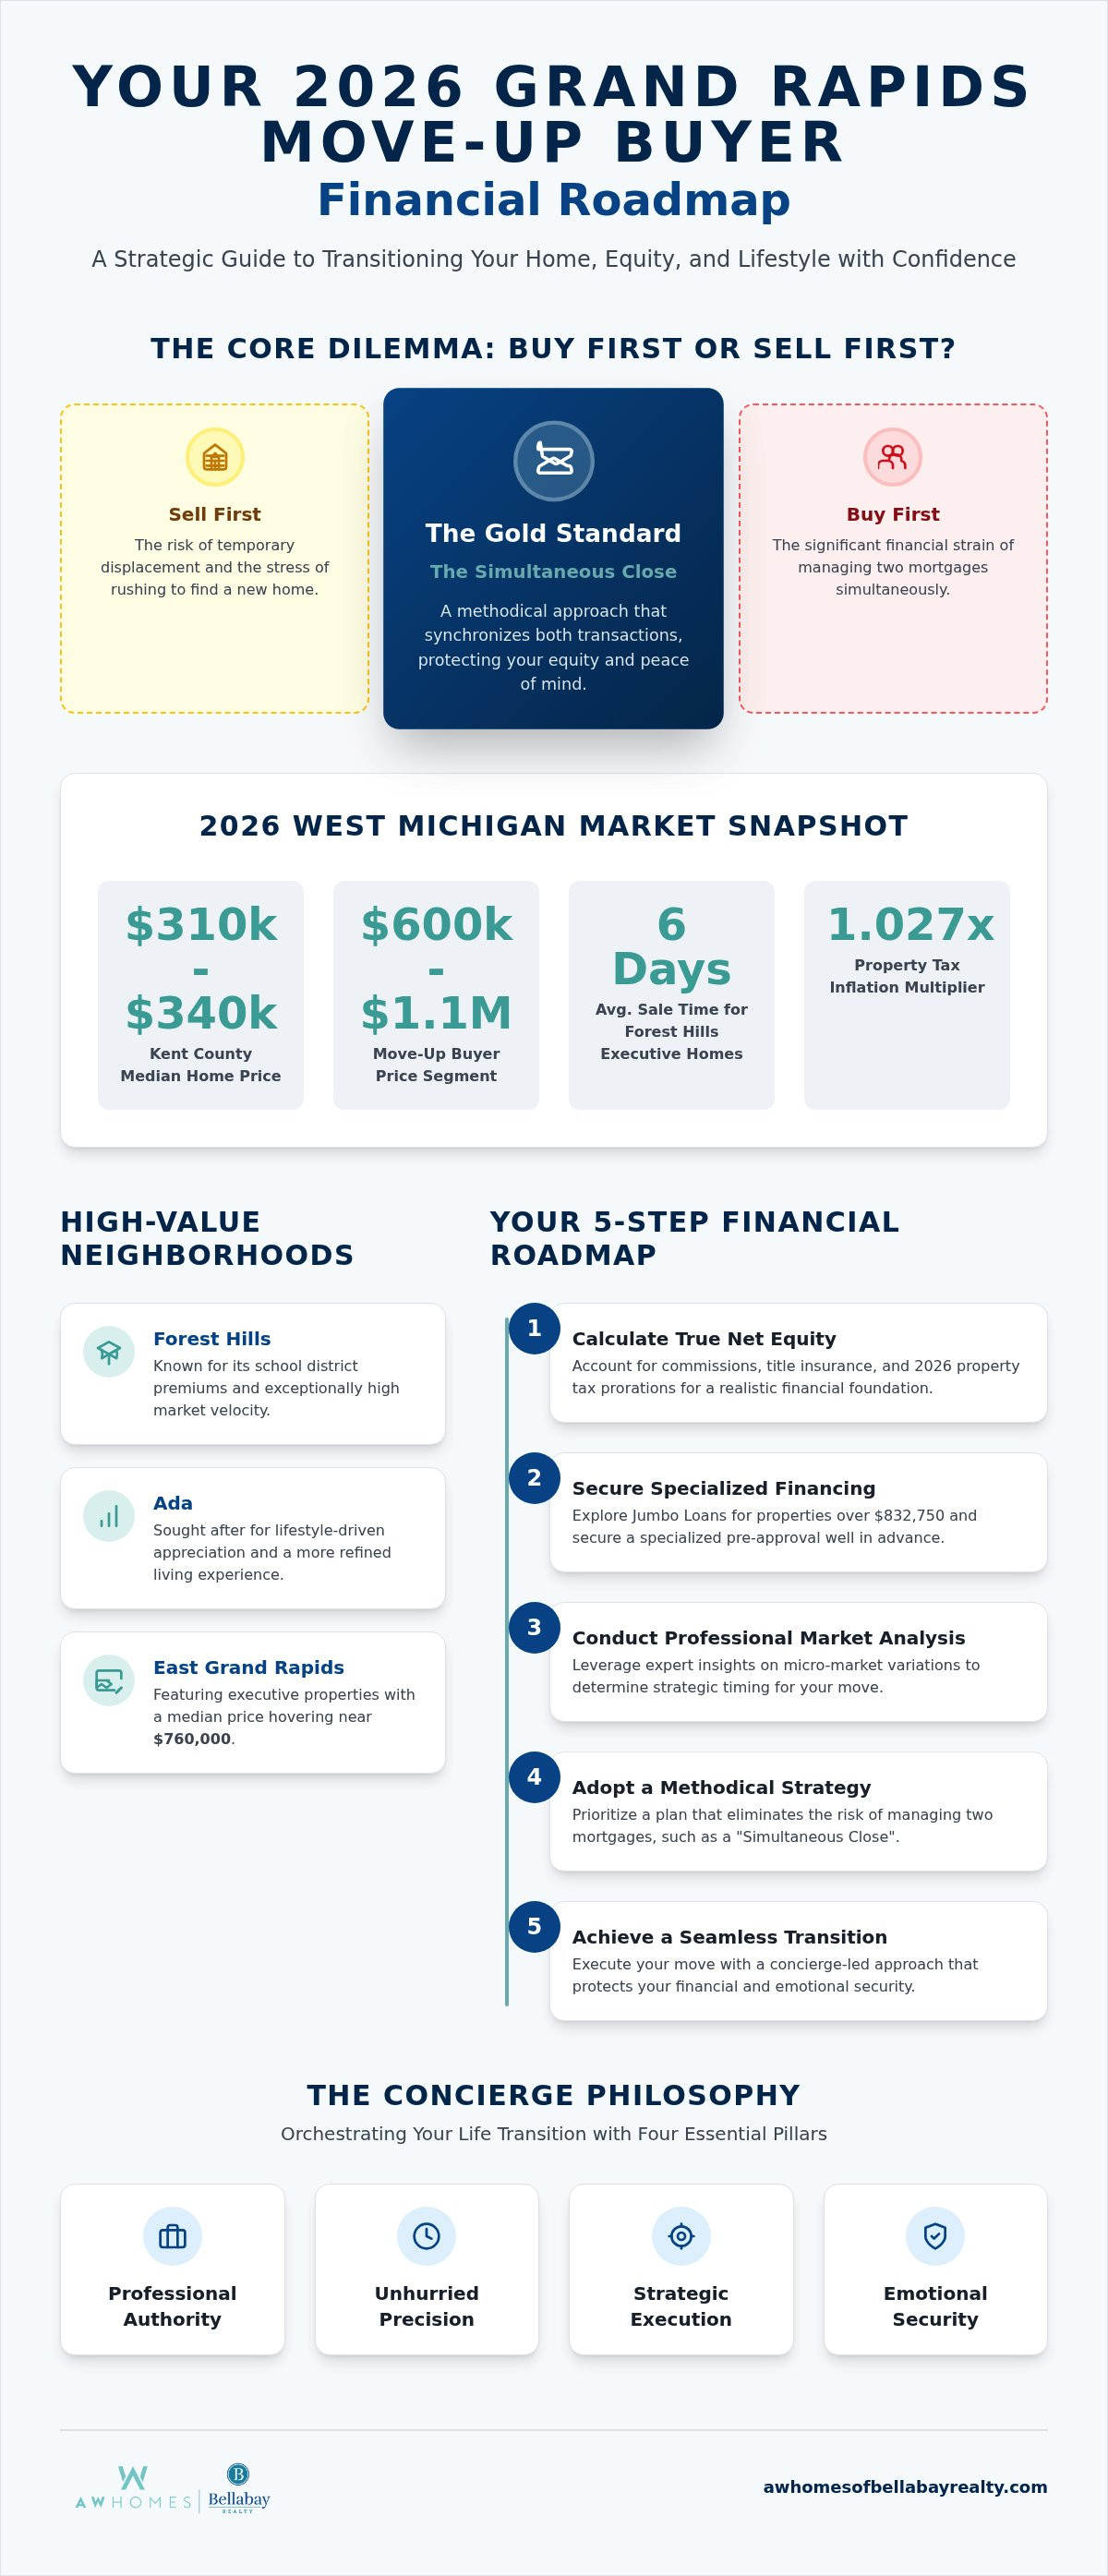
Current Grand Rapids real estate trends indicate a market characterized by stabilization and selective velocity. While median home prices in the broader Kent County area range from $310,000 to $340,000, move-up buyers often find themselves navigating the $600,000 to $1.1 million segment. Inventory remains lean for executive-style homes, making move-up buyer financial planning Grand Rapids a critical prerequisite for success. Understanding these micro-market variations ensures that your next step is both a lifestyle upgrade and a sound financial decision.
The Move-Up Buyer Dilemma: Buy or Sell First?
The central tension of any transition is deciding whether to list your current home or secure your next one first. Selling before you find a new residence in Ada or Cascade risks temporary displacement, creating unnecessary stress for your family. Conversely, purchasing your next home before selling your current one can lead to the significant financial strain of managing two mortgages simultaneously. We specialize in the "Simultaneous Close," which remains the gold standard for West Michigan transitions. This methodical approach synchronizes both transactions, allowing for a seamless move that protects your equity and your peace of mind. Strategic move-up buyer financial planning Grand Rapids helps us bridge this gap with confidence.
Why 2026 Demands a Methodical Approach
The 2026 economic landscape introduces specific variables that demand expert navigation, such as the 1.027 property tax inflation multiplier. Every detail of your transition must be calculated to account for these shifts in carrying costs. Your move is likely driven by personal evolution, whether you need a dedicated home office, a professional-grade kitchen, or additional suites for a growing family. Market velocity in Forest Hills executive homes is exceptionally high, with properties often selling in just six days. This rapid pace means your financial foundation must be established well before you enter the market, ensuring that no detail is left to chance when the perfect property appears.
Maximizing Home Equity and Financing Strategies for Your Next Chapter
Calculated equity is the engine of your next move. In the 2026 West Michigan market, we view this as "Equity Portability," the ability to seamlessly transfer your current wealth into a more refined lifestyle. To begin, you must determine your true Net Equity. This isn't simply your expected sale price minus your current mortgage balance. It's a precise calculation that accounts for brokerage commissions, title insurance, and Michigan’s 2026 property tax prorations. Every dollar must be accounted for to ensure your transition is grounded in reality rather than estimation.
Understanding the home closing process in Michigan is essential to avoid financial surprises at the eleventh hour. For those eyeing executive properties in East Grand Rapids, where median prices hover near $760,000, your financing may cross the 2026 conforming loan limit of $832,750. In these instances, Jumbo Loans become a strategic tool, requiring higher credit scores, larger reserves, and a methodical evaluation of your debt-to-income ratio. Effective move-up buyer financial planning Grand Rapids ensures these technical details are handled with unhurried precision, allowing you to focus on the lifestyle evolution ahead.
Leveraging Your Current Asset: HELOCs and Bridge Loans
If you find your dream home in Ada before your current house is sold, a Home Equity Line of Credit (HELOC) or a Bridge Loan can provide the necessary down payment. With 30-year mortgage rates at approximately 6.96% as of September 2026, these short-term tools require a disciplined look at your monthly cash flow. We often suggest "Seller Post-Occupancy" agreements. This allows you to stay in your sold home for a set period, providing a timing cushion that eliminates the rush, protects your family’s routine, and simplifies the logistics of a single move.
The Role of Recasting in Your Move-Up Strategy
For conservative buyers, mortgage recasting is often the most calming financial choice. Unlike refinancing, which replaces your loan entirely, recasting allows you to make a large principal payment from your home sale proceeds after closing. Your lender then re-amortizes the remaining balance, lowering your monthly payment without changing your interest rate. In a 2026 environment where rates remain higher than previous decade averages, recasting provides immediate cash flow relief. It’s a steady, organized way to align your new mortgage with your long-term well-being. If you are ready to begin this evolution, exploring your options with a strategic advisor can clarify your path forward.
Comparing High-Value Neighborhoods: Forest Hills, Ada, and East Grand Rapids
Selecting the right neighborhood for your next life stage is a decision that balances stability, prestige, and lifestyle. In West Michigan, high-value enclaves each offer distinct financial profiles that influence your long-term wealth. East Grand Rapids remains a pinnacle of stability and demand. With a median home price between $740,000 and $760,000 in mid-2026, the market here is defined by extreme scarcity. Homes in this community often sell within seven days, reflecting a persistent desire for walkable, executive-level living. This high demand ensures that your equity is protected by a neighborhood with historically resilient values.
In contrast, Ada MI offers a different landscape of growth and expansive luxury. The median listing price in Ada reached $1.1 million in August 2026, driven by a surge in luxury estates and lifestyle-driven appreciation. While the market for homes above $1 million can see a slower pace with a median of 38 days on market, it offers unparalleled leverage for buyers seeking custom builds and larger acreage. Forest Hills also continues to be a primary destination for move-up buyers, with a June 2026 median sale price of $647,000. For a deeper exploration of these high-end markets, our guide to luxury homes Grand Rapids MI provides a comprehensive analysis of West Michigan’s finest estates.
School Districts and Long-Term Value Retention
The academic reputation of a neighborhood is a primary driver of its real estate resilience. Forest Hills Central and Northern districts serve as powerful anchors for local property values, as buyers consistently prioritize academic reputation, extracurricular excellence, and community investment. We define Educational Equity as the inherent financial value added to a property by its proximity to top-tier public school systems. This factor stabilizes resale prices even during broader market shifts. Furthermore, the presence of Ada Christian and other private options in the immediate area creates a layered demand that supports high-stakes move-up buyer financial planning Grand Rapids.
Tax Considerations: Caledonia vs. Cascade
Millage rates and property tax structures are essential components of your monthly move-up budget. In East Grand Rapids, the median effective property tax rate is approximately 1.57%, which is significantly higher than the broader Grand Rapids average of 0.86%. It's vital to understand Michigan’s Proposal A when transitioning between municipalities. Upon purchase, your new home’s taxable value will "uncap" and reset to 50% of the current market value. This reset can lead to a substantial increase in annual costs compared to what the previous owner paid. Methodical move-up buyer financial planning Grand Rapids requires a detailed analysis of these millage rates, taxable values, and uncapping rules to ensure your transition remains tax-efficient and predictable.
Your Step-by-Step Financial Roadmap for a Seamless Move-Up
A move-up transition is a curated journey that requires a steady hand and a methodical plan. To move with confidence in 2026, your strategy must be grounded in data, timing, and professional oversight. This roadmap ensures that move-up buyer financial planning Grand Rapids moves beyond simple spreadsheets and into a comprehensive life strategy. By following these structured steps, you protect your equity, your time, and your emotional security.
- Step 1: Conduct a Professional Comparative Market Analysis (CMA). Your journey begins with a realistic valuation of your current asset. We provide a deep analysis of 2026 market trends in your specific neighborhood to determine your likely net proceeds.
- Step 2: Secure a specialized "Move-Up Pre-Approval." This is more than a standard letter; it's a strategic document that accounts for your equity position and potential bridge financing, giving you the power of a cash buyer. For insights into how these standards are applied in other competitive markets, Integrity Estates Realty provides a detailed roadmap for securing your financial foundation.
- Step 3: Audit your "Transition Fund." We help you identify the necessary capital for moving costs, staging, and minor repairs. Having these funds liquid prevents last-minute stress.
- Step 4: Execute a strategic selling plan. To maximize your net proceeds, you need to follow a tailored sell my home Forest Hills MI strategy that highlights your property's unique value to executive buyers.
- Step 5: Negotiate with "Transition Contingencies." We use specific contractual clauses to protect your financial security, ensuring the sale of your current home and the purchase of your next one are perfectly synchronized.
Budgeting for the "Hidden" Costs of Moving Up
Transitioning to a larger home in Ada or Cascade involves financial nuances that go beyond the purchase price. Professional staging and executive-level photography are essential investments in 2026 to ensure your current home stands out in a competitive market. You must also account for "lifestyle creep," which includes increased utility costs and property tax uncapping. We advise our clients to establish a 1% annual Maintenance Reserve. This fund ensures that your larger estate remains a source of pride rather than a source of stress. If you're ready to begin this methodical process, connect with our team for a personalized equity assessment.
Orchestrating the Timing: The 90-Day Transition Window
Timing is the ultimate anchor of a stress-free move. We focus on a 90-day transition window that aligns your listing date with peak buying seasons in West Michigan. This period allows for the strategic management of earnest money deposits while your primary capital is still tied up in your current residence. Our methodical checklist covers every detail from the initial audit to the final walkthrough. By focusing on unhurried precision, we ensure that your move-up buyer financial planning Grand Rapids results in a seamless, professional, and celebratory closing day.
The AW Homes Concierge Approach: Orchestrating Your Life Transition
At AW Homes of Bellabay Realty, we believe that a high-stakes real estate transaction is more than a trade of assets; it is a profound personal milestone. Our Concierge philosophy is defined by three core pillars: professional authority, unhurried precision, and strategic intentionality. We move beyond the standard role of a listing or buying agent to act as your high-level consultant. By positioning your move within the broader context of your personal evolution, we mitigate the inherent stress of the 2026 market. Our team manages every detail of the transaction pipeline to ensure that your emotional security remains the ultimate anchor of the process.
Effective move-up buyer financial planning Grand Rapids requires a partner who views the process as a curated journey. We don't just find houses; we orchestrate transitions that respect your time and your family's long-term well-being. Whether you are navigating the rapid six-day market velocity in Forest Hills or the expansive luxury estates of Ada, our methodical approach ensures that no detail is left to chance. We provide the steady, knowledgeable guidance necessary to navigate complex fiscal requirements while you focus on the excitement of your next chapter.
Tailored Expertise for Every Life Stage
Our expertise is specifically tailored to the nuances of different life stages. We specialize in assisting families who are outgrowing their starter homes and are ready to establish roots in executive estates. This transition requires a sophisticated understanding of how to leverage current equity while securing high-value financing in communities like Cascade and East Grand Rapids. For our relocation clients, we act as a regional authority, providing the localized reliability needed to make a confident move to West Michigan. Our regional dominance in these high-end enclaves provides you with significant negotiation power and deep market insight that generalist competitors simply cannot match.
Beyond the Transaction: A Partner in Your Evolution
Our commitment to your success extends far beyond the final signature on a closing document. We serve as a dedicated partner in your evolution, providing access to an elite local vendor network that includes specialized inspectors, interior designers, and white-glove moving services. These resources are integrated into our seamless process, ensuring that every logistical hurdle is cleared before it can create friction. The Angela Worth Edge in move-up financial planning is the integration of high-level fiscal strategy with a profound understanding of the emotional milestones inherent in every life transition. We prioritize your long-term well-being over a quick closing, maintaining a composed and attentive presence from our first meeting to your move-in day.
If you are ready to master the financial complexities of your next move, it's essential to find a buyers agent Grand Rapids partner who understands the specific demands of luxury transitions. We invite you to schedule a strategic move-up consultation with Angela Worth’s team to begin building your personalized roadmap. Let us provide the professional authority and empathetic reassurance you deserve as you step into your future.
Stepping Into Your Next Chapter with Confidence
Your transition to an executive estate in Forest Hills, Ada, or East Grand Rapids is a significant personal milestone that deserves a methodical, unhurried strategy. We've explored how a synchronized financial bridge, specialized pre-approvals, and neighborhood-level analysis can turn a complex move into a seamless evolution. By prioritizing emotional security and technical precision, you ensure that your current home equity effectively fuels your future ambitions. No detail should be left to chance when you are orchestrating a high-stakes life transition.
Mastering move-up buyer financial planning Grand Rapids is the key to navigating 2026 market shifts while protecting your family's long-term well-being. With over 15 years of West Michigan real estate expertise and a specialized concierge approach, Angela Worth’s team is dedicated to providing the localized reliability you need. We understand the nuances of our region's most desirable enclaves and the financial strategies required to secure them. If you're ready to align your financial foundation with your lifestyle goals, Schedule Your Strategic Move-Up Consultation with Angela Worth today. Your next life stage is a positive evolution, and we're here to ensure you arrive with total peace of mind.
Frequently Asked Questions
Can I buy a new home in Grand Rapids before selling my current one in 2026?
Yes, you can certainly purchase your next residence before selling your current one. In the 2026 market, many buyers utilize bridge loans or home equity lines of credit to make non-contingent offers. This approach is particularly effective in competitive areas like East Grand Rapids where homes often sell in seven days. However, this path requires a steady financial foundation and a clear understanding of your debt-to-income ratio to ensure your transition remains unhurried and secure.
What is a bridge loan and is it right for a move-up buyer in West Michigan?
A bridge loan is a short-term financing tool designed to cover the gap between purchasing a new home and selling your existing property. It is often an ideal solution for move-up buyers in Ada or Forest Hills who want to make competitive, non-contingent offers. While these loans provide significant leverage in a seller's market, they also carry specific interest considerations. We analyze your equity position to determine if this methodical approach aligns with your long-term well-being.
How does the 2026 interest rate environment affect move-up buyer financial planning?
As of September 2026, 30-year fixed mortgage rates in Michigan are approximately 6.96%. This environment makes move-up buyer financial planning Grand Rapids essential for maintaining your purchasing power. Higher rates demand a more strategic focus on debt management and equity portability. We help you navigate these shifts by identifying financing structures, such as mortgage recasting, that can significantly lower your monthly obligations once your current residence successfully closes in the West Michigan market.
What are the most tax-efficient neighborhoods in Greater Grand Rapids for luxury homes?
Tax efficiency varies significantly across West Michigan enclaves. Grand Rapids offers a median effective property tax rate of 0.86%, while East Grand Rapids is approximately 1.57%. You must also account for Michigan’s Proposal A, which resets your taxable value to 50% of the market value upon purchase. We provide a detailed millage rate analysis for Caledonia, Cascade, and Ada to ensure your monthly budget remains predictable, sustainable, and aligned with your personal evolution.
How much equity do I need in my current home to afford a move-up purchase?
Most families find that having 20% to 30% equity in their current residence provides a comfortable foundation for a move-up purchase. This capital typically covers your next down payment, closing costs, and a maintenance reserve for a larger estate. Calculating your "Net Equity" is a critical first step in our concierge process. We subtract commissions and prorated taxes to give you a precise figure, ensuring your life transition is grounded in financial reality rather than estimation.
What happens if my current home sells faster than I can find a new one?
If your home sells rapidly, we utilize strategic tools like "Seller Post-Occupancy" agreements to provide a necessary timing cushion. In Forest Hills, where executive homes often sell in just six days, this protection is vital. These agreements allow you to remain in your home for a set period after closing, giving you the space to find the perfect next residence. Our goal is to mitigate stress and ensure you never feel rushed during your transition.
Does AW Homes assist with the staging and marketing of my current property?
Yes, our concierge-style approach includes comprehensive residential listing services. We coordinate professional staging, executive-level photography, and strategic market positioning to maximize your net proceeds. These services are essential in the 2026 market to distinguish your property and attract high-value buyers. By managing the transaction pipeline from our first meeting to the final signature, we ensure every detail of your home’s presentation is professional, unhurried, and highly effective for West Michigan sellers.
How do I manage two mortgages during a move-up transition?
Managing two mortgages requires a methodical plan focused on cash flow and timing. We often recommend a simultaneous close to synchronize both transactions, which is the gold standard for a stress-free transition. If a gap exists, options like mortgage recasting can be applied after your sale to reduce the principal on your new loan. This strategy provides immediate relief and aligns your new debt with your equity position, protecting both your emotional security and your financial stability.


