
The lender with the lowest advertised rate may not be the best fit for your Cascade purchase. When buying a home in Cascade MI, compare more than a headline number: loan terms, upfront costs, timing, and communication all matter.
It’s understandable to feel unsure about which lender type suits your finances or how to judge competing offers. A clear comparison can help you prepare for a competitive or unfamiliar market without rushing your decision. This guide explains how to build a practical lender shortlist, review each Loan Estimate, and check a lender’s credentials and service approach.
You’ll also learn how to start financing conversations before your home search gathers pace, and what to ask about preapproval and closing timelines. A local buyer’s agent can help coordinate property research and offer timing with the lender you choose, while leaving mortgage guidance to that lender. Comparing terms, service, and readiness can help you move toward your Cascade home purchase with greater confidence.
Key Takeaways
- When buying a home in Cascade MI, match your lender search to your finances, property plans, loan needs, and timeline.
- Compare lender categories as starting points, then verify each lender’s terms, credentials, and communication practices.
- Look beyond the advertised rate: weigh APR, fees, points, estimated cash to close, and rate-lock terms together.
- Prepare consistent financial information before requesting comparisons, then use your chosen lender’s guidance to plan preapproval and offer readiness.
- Keep lender selection in your hands while coordinating property research and offer timing with local buyer representation.
Buying a Home in Cascade, MI: Start With the Right Financing Questions
Lender choices can feel confusing when you’re also weighing homes, neighborhoods, and how each property may fit your plans. Start by identifying what you need from financing instead of choosing a lender based on one number or recommendation. The right fit depends on your finances, the type of home you’re considering, your loan needs, the lender’s communication, and your timing.
A preapproval is a lender’s review of your financial information that can help clarify a potential borrowing range. It isn’t a guarantee of final loan approval, and the amount a lender may allow you to borrow isn’t necessarily what you’ll feel comfortable paying each month. If you’re new to the process, this mortgage loan overview introduces the basic relationship between borrower, lender, and property.
Cascade is part of the Greater Grand Rapids home-search area, but location details can vary from one property to another. Confirm the jurisdiction and address-specific information for each home you consider.
What should Cascade homebuyers decide before contacting lenders?
Set a comfortable monthly housing budget, then consider the full cash picture. Think through your planned down payment, how much savings you want to retain after closing, the property types you’re open to, and your expected move timing. Sharing these details can help lenders discuss your circumstances more meaningfully. Each lender assesses buyers individually, so ask how your finances and plans affect the options they can explain.
Why does the property location matter to financing?
Two homes at similar prices can have different ownership costs. Property taxes, insurance, utilities, and other expenses depend on the home and its location, so include them in your budget rather than focusing on the mortgage payment alone. Verify school boundaries, township services, and property details using the specific address. Don’t assume a neighborhood label tells the whole story.
As you evaluate a particular home, investigate relevant flood risk, property condition, and appraisal considerations. These can affect your assessment of the property and the financing process. Ask your lender which property-related details they need to review, and use reliable local sources to verify address-specific information. A clear picture of both your finances and the property can make your next financing conversation more focused.
Mortgage Lender Options for a Cascade, MI Home Purchase
There’s no universal “best” lender for buying a home in Cascade MI. Treat lender categories as starting points, not a ranking: available options, eligibility, terms, and service can differ by institution and buyer. Ask each lender for current written details based on the same purchase assumptions so you can make a fair comparison.
| Lender type | Possible strengths | Questions to ask | Items to verify |
|---|---|---|---|
| Local bank or credit union | May offer familiar local contacts or experience with area transactions. | What local processing experience do you have? How will you coordinate closing? | Membership or eligibility, loan options, fees, timelines, and servicing. |
| Mortgage broker | May compare offers from lenders in the broker’s network. | Which lenders do you work with? How is compensation handled? | Lender panel, loan issuer, written terms, and who handles underwriting questions. |
| National lender | May provide established online tools or multiple communication channels. | Who will be my contact? How are documents and questions handled? | Availability of the loan option, fees, closing coordination, and servicing. |
A Loan Estimate is a written form from a lender that summarizes estimated loan terms and costs, giving buyers a consistent basis for comparing offers. The Consumer Financial Protection Bureau provides tools and resources for homebuyers, including guidance on comparing loans. Request current documents and ask the lender to explain any figures or terms you don’t understand.
How do local banks and credit unions compare with national lenders?
Ask local institutions about their experience processing purchases in the Greater Grand Rapids area, how they communicate, what options they offer, and how they coordinate with the parties involved in closing. Don’t assume a local institution automatically offers a better rate, service, or approval likelihood. Confirm eligibility, fees, expected timelines, and whether the institution will service the loan after closing directly with its representatives.
When might a mortgage broker be worth comparing?
A broker may present options from lenders they work with, but that lender panel may not include every available lender. Ask how compensation works, which institution would issue the loan, and who will answer questions during underwriting. Then compare the broker’s written options with direct lender offers using consistent assumptions about the purchase, down payment, and loan terms.
For a more coordinated home search, keep lender selection and loan advice with the professionals who provide them, while coordinating property research and offer timing with your buyer’s agent. Buyers looking for local context can explore Cascade buyer representation as part of their purchase planning.
How to Compare Grand Rapids Mortgage Lenders Beyond the Advertised Rate
A low advertised interest rate can catch your attention, but it doesn’t show the full cost or explain how a loan fits your plans. When buying a home in Cascade MI, compare the complete written offer, including fees, cash needed at closing, and how the lender handles questions and timing. Don’t rely on rates or verbal estimates that aren’t based on your circumstances and current details.
Which details should buyers compare on written loan estimates?
Ask each lender to prepare an estimate using the same loan amount, down payment, loan term, property assumptions, and expected timing. Then review these items side by side:
- Interest rate and APR: The interest rate affects borrowing costs, while the annual percentage rate (APR) reflects the rate plus certain loan costs. Compare both and ask what is included in the APR.
- Estimated payment: Check what the monthly figure includes, such as principal and interest, mortgage insurance, and estimated taxes or insurance. Confirm which amounts may change.
- Fees and points: Review lender charges and any discount points or credits. Ask what each charge covers and whether points are optional.
- Cash to close: Compare the estimated amount due at closing. Separate lender charges from third-party costs, such as services or items arranged outside the lender, and ask the lender to explain each line.
- Loan structure and rate lock: Confirm whether the rate is fixed or adjustable, whether a rate lock is included, how long it lasts, and what terms or conditions apply.
Also ask when the estimate expires and what could change its figures, such as a different purchase price, property details, or updated financial information. An estimate is useful for comparison, but it isn’t a promise that final terms will stay unchanged.
How can service and timing affect the lender decision?
Clear communication matters as you move from home search to offer and closing. Ask who will manage your application, respond to underwriting questions, request documents, and provide status updates. Find out how to reach that person and how the lender shares important changes.
Compare the lender’s expected timeline with your preferred offer and closing schedule. A quick initial response doesn’t necessarily indicate how smoothly later steps will proceed, so ask what milestones to expect and what might delay them. Judge responsiveness by the clarity and consistency of the answers, not by verbal promises. Request material terms in writing, and ask the lender to explain anything that differs from the estimate.
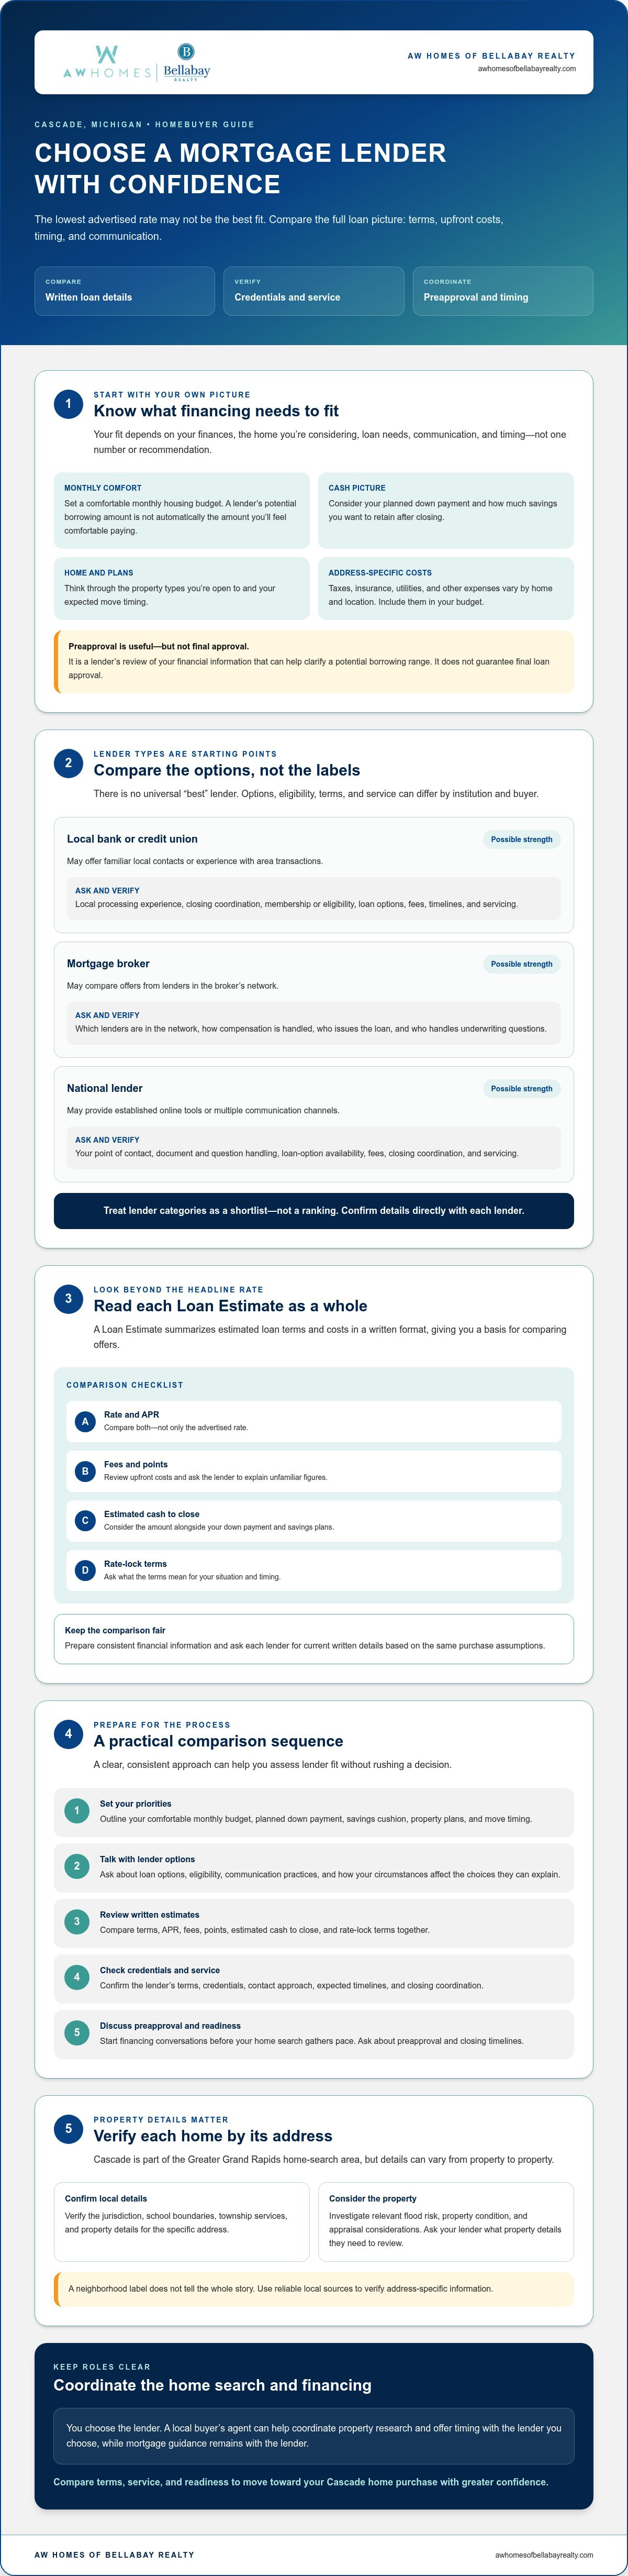
A Cascade Homebuyer’s Step-by-Step Mortgage Comparison Checklist
A repeatable process makes lender conversations easier to assess. Before buying a home in Cascade MI, gather the same information for each lender and compare written estimates built around the same purchase assumptions. Keep your own notes so the decision reflects both the numbers and the service you need.
- Set a comfortable payment range. Decide what monthly housing cost feels manageable instead of relying only on a lender’s maximum borrowing estimate. Leave room in your budget for ownership expenses that vary by property.
- Map out your available funds. Note the amount you may put toward the down payment and how much savings you want to keep after closing. Ask lenders to explain how their estimates account for funds due at closing.
- Organize financial information. Gather income, asset, debt, and identity documents as requested by each lender. Protect sensitive records and submit them only through channels the lender confirms are approved and secure.
- Clarify your purchase plans. Identify likely property types and your expected move timing. Ask each lender whether those details affect the options, requirements, or timeline they can discuss.
- Verify program details directly. If you’re exploring a particular loan program, ask a qualified lender to confirm your eligibility and explain current requirements. Don’t assume a program applies based on a general description or another buyer’s experience.
- Request comparable written estimates. Use the same loan amount, down payment, term, and timing when asking lenders for estimates. Compare the rate, APR, fees, points or credits, estimated payment, cash to close, and rate-lock terms. Ask for clarification on unfamiliar conditions.
- Compare the service plan. Record each lender’s main contact, expected response time, document requests, and estimated transaction timeline. If an offer differs substantially from the others or includes a condition you don’t understand, ask for another explanation before deciding.
- Prepare for preapproval and an offer. Ask the lender what information remains outstanding and what the preapproval does and doesn’t establish. Coordinate the lender’s timing with your home search and offer preparation, then review later transaction milestones in a Michigan home closing process guide.
Once you have a clear financing comparison, local buyer representation can help coordinate property research and offer planning alongside the lender you choose. Explore Cascade buyer representation with AW Homes as you prepare for your next steps.
Coordinate Your Cascade Home Search, Lender, and Offer With AW Homes
Financing and a home search move on connected timelines, but they’re separate areas of expertise. Your lender explains financing, reviews your information, and sets out loan terms. Your buyer’s agent helps you explore properties, understand local context, and plan an offer. Coordinating those conversations can make buying a home in Cascade MI feel more orderly while keeping each decision with the right professional.
AW Homes of Bellabay Realty, led by Angela Worth, represents buyers in Cascade and the Greater Grand Rapids area, including Grand Rapids, Ada, Caledonia, and East Grand Rapids. The team doesn’t provide mortgage lending or financial advice, and lender selection stays with you. Financing readiness can help inform when you’re prepared to make an offer, but it can’t guarantee loan approval or that a seller will accept your offer.
What can a buyer’s agent help coordinate in Cascade?
Buyer representation can include property sourcing, comparative market analysis, and contract negotiation. As you evaluate homes, an agent can help organize property-specific questions for the appropriate professional. Questions about loan terms belong with your lender, while inspection questions should go to an inspector. An agent can help keep the home search and offer-planning conversations connected, but doesn’t assess whether a loan suits your finances or promise a particular transaction outcome.
Local context matters, too. Comparing properties can involve looking beyond listing details to consider how each home fits your priorities and plans. Your agent can help you evaluate available property information and prepare an offer strategy, while your lender confirms financing details and timing for your circumstances.
What should buyers bring to an initial home-search conversation?
You don’t need to have every financing decision settled before discussing your search. Bring a starting point: preferred areas, property needs, approximate move timing, and where you are in conversations with lenders. If you’re still comparing options or have questions about preapproval, say so. That context helps shape a realistic search and makes it easier to coordinate next steps with the lender you choose.
Useful questions might include which property features are priorities, what trade-offs you’re open to, and how quickly you hope to move. New questions are expected as your search develops. Keep mortgage and eligibility questions with your lender, and share relevant timing updates so property research and offer planning can stay aligned.
If you’re ready to discuss your Cascade home search, preferred areas, and next steps, talk with AW Homes of Bellabay Realty about your Cascade home search. You can begin with questions and build a thoughtful plan from there.
Move Toward Your Cascade Home Search With a Clear Plan
Buying a home in Cascade MI starts with decisions that work together: set a comfortable budget, compare lenders using written terms beyond the advertised rate, and prepare financing questions before making an offer. Preapproval can help clarify a potential borrowing range, while your chosen lender remains the source for loan terms, eligibility, and approval.
AW Homes serves buyers in Cascade and the Greater Grand Rapids area, including Grand Rapids, Ada, Caledonia, and East Grand Rapids. Buyer representation can bring local property research and offer planning into focus through services that include property sourcing, comparative market analysis, and contract negotiation. Your lender handles financing. Coordinated conversations can help keep the home search and transaction steps aligned without promising a particular outcome.
Ready to discuss your preferred areas, property needs, or where you are in the search? Talk with AW Homes about your Cascade home search and take the next step with a clear plan.
Frequently Asked Questions
How do I choose a mortgage lender when buying a home in Cascade, MI?
Start with your comfortable budget, property plans, and financing needs, then compare written estimates from several lender options. When buying a home in Cascade MI, look beyond the advertised rate: review fees, estimated cash to close, rate-lock terms, communication, and timing. Ask each lender to explain its assumptions and confirm current terms and eligibility directly. Offers depend on your circumstances and may change, so treat initial estimates as comparison tools, not guarantees.
Should I use a local bank, credit union, mortgage broker, or national lender?
No single lender type suits every Cascade buyer. A local bank or credit union, broker, or national lender may differ in available loan options, eligibility, compensation, processing, and service. Ask who issues and handles the loan, how questions are answered, and what fees and timelines apply. Request written estimates based on the same assumptions, then verify lender availability and licensing details directly before choosing.
Can a real estate agent recommend a mortgage lender?
A real estate agent can help coordinate the home search and offer timing with the lender you select, but you should independently assess lenders and loan terms. Ask whether a referral involves a business relationship or compensation, and compare options yourself. AW Homes provides buyer representation, not mortgage lending or financial advice. Direct questions about rates, eligibility, and loan suitability to qualified lenders, and confirm terms in writing.
What should I compare besides a mortgage interest rate?
Compare the APR, lender fees, points or credits, estimated monthly payment, cash to close, and rate-lock terms. Check whether mortgage insurance or adjustable-rate features apply, and ask what the payment estimate includes. Use the same loan amount, down payment, and term for each comparison. If an advertised rate differs from your written estimate, ask the lender to explain the assumptions and conditions that affect the terms available to you.
How do I get preapproved for a mortgage before buying in Cascade?
Contact lenders to learn about their application steps, requested documents, credit review, and estimated timeline. Provide financial and identity information only through submission channels the lender confirms are secure. Ask what the preapproval reflects and what it doesn’t confirm; it isn’t a guarantee of final financing. If your finances, purchase plans, or target property change, contact the lender to check whether your preapproval information or estimated terms need updating.
Are FHA, VA, or USDA loans available for homes in Cascade, Michigan?
Potential availability depends on the buyer, property, current program requirements, and lender participation. Don’t assume a home qualifies because it’s in Cascade, or that you qualify based on a general program description. Ask lenders to explain eligibility, costs, property requirements, and timing for your circumstances. Before relying on a program in your purchase plan, confirm current rules with the relevant official source and the lender handling your application.
When should I compare mortgage lenders during a Cascade home search?
Begin lender conversations before you’re ready to make an offer. That gives you time to understand document requests, possible financing options, and estimated timing. Compare written terms when available, and refresh the information if your finances, rates, or target property change. Coordinate the expected financing timeline with your agent, whether you’re searching in Cascade, Grand Rapids, Ada, Caledonia, or East Grand Rapids. Confirm loan terms and commitments directly with your lender.


